The political landscape in Washington has grown significantly tense following President Donald Trump’s surprise decision to cancel the signing ceremony for the 21st Century ROAD to Housing Act, which was scheduled to take place at the Capitol.
Trump made it clear on social media that he will not sign this legislative package until Congress approves the SAVE America Act, a strict electoral reform proposal that would require physical proof of citizenship (such as a passport or birth certificate) to register and vote in federal elections. The president described the electoral situation as a “national emergency” that overshadows all other priorities.

Key points of the conflict
- Awkward timing for Republicans: Trump’s announcement came just as Republican leadership in the House of Representatives was holding a press conference praising the housing bill. House Majority Leader Steve Scalise had just called it a “crucial tool for reducing housing costs” when reporters informed him of the president’s snub.
- Criticism of the bill: Trump labeled the housing legislation as “Warren-centric,” referring to Democratic Senator Elizabeth Warren (a co-sponsor of the bill), and claimed the law is of “lesser importance” compared to electoral reform, interest rates, or the FISA surveillance law.
- A bill with massive support: The housing package is the result of months of negotiations and combines proposals from over 60 previous bills. It passed the Senate 85-5 and the House 358-32. The bill limits the ability of large institutional funds to buy single-family homes, eases certain zoning regulations to speed up the construction of affordable housing, and modernizes rental assistance programs.
What happens now?
Despite the president’s public rebuff, congressional leaders are trying to calm the waters and find a technical and political solution:
- The clock strategy (The 10-day window): Constitutionally, once Congress formally delivers the bill to the president, he has 10 days (excluding Sundays) to act. If he neither signs nor vetoes it while Congress is in session, the bill automatically becomes law. House Speaker Mike Johnson has suggested Trump is simply running down the clock to apply pressure and believes he will eventually back down.
- A veto-proof majority: If Trump decides to formally veto the bill to keep his word, both chambers of Congress have the supermajorities (over two-thirds) needed to override the presidential veto and force the housing law into effect.
- Alternative path for electoral reform: To break the logjam created by Trump and more conservative lawmakers—who have threatened to block all House activity until the citizenship voting measure is debated—Johnson is meeting with the president to propose including key parts of the SAVE America Act in a budget reconciliation bill. This would bypass the Senate’s Democratic filibuster and allow the electoral reform to pass with a simple majority.
How the playing field changes for families
The legislation defines a large institutional investor as any corporation or entity that owns 350 or more single-family homes. By restricting their purchases, the impact on regular buyers is twofold:
- Fewer unbeatable cash offers: Private equity funds typically buy properties by paying 100% of the value upfront, without financing contingencies, and close deals within days. A traditional buyer, who depends on mortgage approval, rarely stands a chance against such offers. Removing these funds from the equation means families will compete against other families on a level playing field.
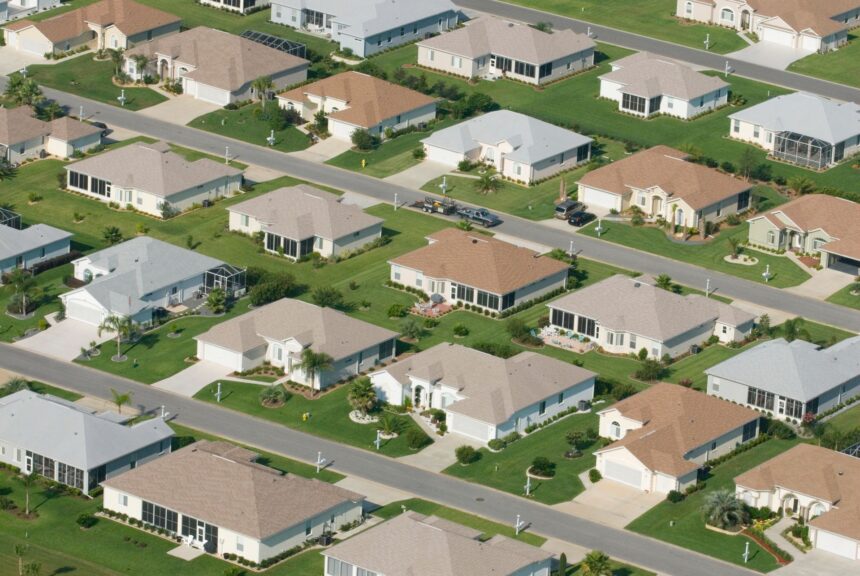
- Protection for “starter homes”: Wall Street doesn’t usually buy luxury mansions. Their business model focuses on starter homes (low- to mid-priced single-family homes). These are exactly the properties renters need to transition into homeownership.
The fine print and exceptions
The House of Representatives amended the bill to ensure the ban does not halt the creation of new housing. As a result, funds can still operate under certain key exceptions:
- Build-to-Rent: Corporations can continue investing if they build entirely new homes from the ground up, adding fresh inventory to the market.
- Renovate-to-Rent: They are allowed to purchase severely deteriorated properties—those a regular buyer could neither inhabit nor finance through a bank—rehabilitate them, and place them on the rental market.
- No forced liquidation: The rule applies to future purchases (180 days after the law takes effect). Funds are not required to immediately sell their existing inventory but will face fines of up to one million dollars, or three times the property’s value, if they illegally attempt to buy existing homes.
Political expectations vs. economic reality
While the measure is overwhelmingly popular among voters from both parties, economists and institutions like the Urban Institute warn that this ban will not cause a drastic drop in home prices nationwide.

Data shows that, despite public perception, large institutional investors currently own less than 0.5% of all single-family homes in the United States and about 3% of the rental inventory. While their presence in certain neighborhoods may drive up local prices, the root cause of high costs at the macroeconomic level is the chronic lack of new housing construction over the past decade.
Image: ElHispanoParaTodos/PRESS