The Standoff Over Your Money: Why the Fed Said ‘No’ to White House Pressure
If you were hoping your credit card payment would magically drop this month, the news from Washington just delivered a reality check. In a move many are calling an “institutional rebellion,” the Federal Reserve (Fed) decided today to keep interest rates unchanged at a range of 3.50% to 3.75%.
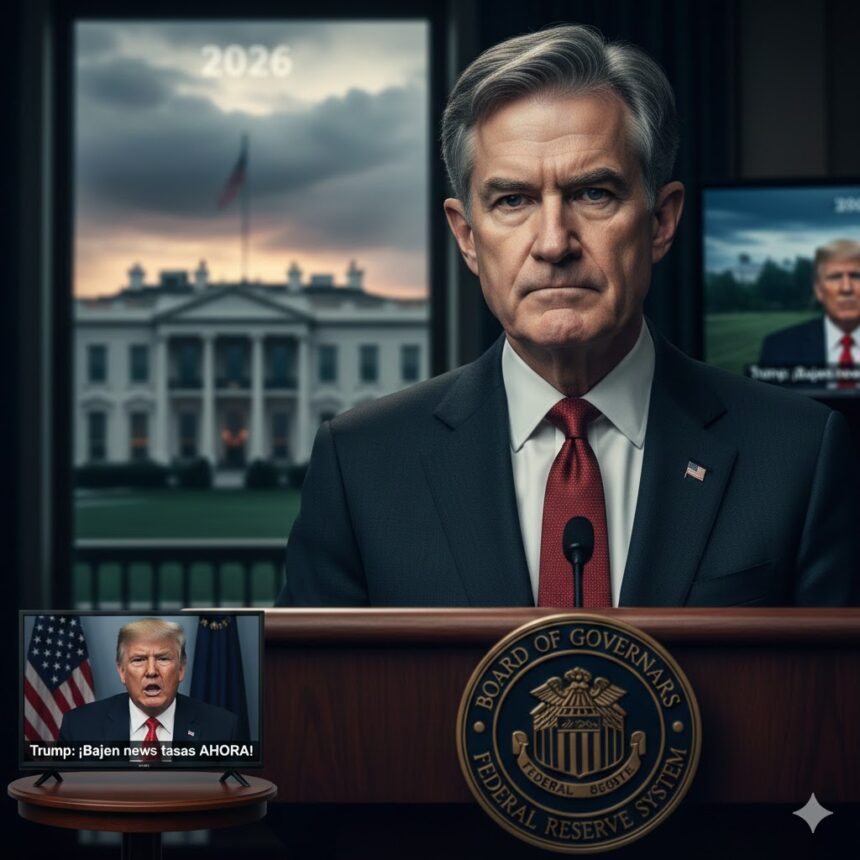
Why is this controversial? Because it’s happening amid an open war. President Donald Trump hasn’t stayed quiet: he wants lower rates to “inject adrenaline” into the economy. But Jerome Powell, the man in charge of the Fed (for now), has other data. Inflation isn’t fully under control, and offering cheap money now could be like pouring gasoline on the fire of supermarket prices.

Quick Take (Snippet Bait): The U.S. Federal Reserve decided to hold interest rates steady between 3.50% and 3.75% at its January 2026 meeting. Despite pressure from President Trump for aggressive cuts, the Fed justified its pause due to persistent inflation at 2.7% and economic growth it describes as “solid.” For Hispanic consumers, this means interest rates on mortgages and credit cards won’t see immediate relief this quarter.


Powell vs. Trump: Who Really Controls Your Wallet?
The truth is, the Federal Reserve’s independence is hanging by a thread. Powell’s term ends in May of this 2026, and Trump is already sharpening his pen to appoint a more “obedient” successor.
Here’s the interesting part: today’s vote was 10 to 2. Two governors (Waller and Miran), both seen as allies of the current administration’s hardline faction, voted to lower rates. This tells us the internal fracture has already begun. Do we really need the government controlling the price of money? History shows that when politics interferes with interest rates, inflation often spirals out of control.
Chart: The Real Impact on Your Finances (January 2026)
| Financial Product | Current Status | Hispano Nexus Forecast |
| 30-Year Mortgages | Average 6.5% – 6.8% | Will remain high; not yet time to refinance. |
| Credit Cards | APR above 21% | Warning: The cost of debt will continue to squeeze monthly spending. |
| Auto Loans | 7.5% – 9% | Stable, but with stricter approval criteria. |
| Savings Accounts | 4.0% – 4.5% | Opportunity: Still a good time to save cash. |
Three Reasons the Fed Didn’t Cave (And Why It Should Matter to You)
- The Ghost of 2.7%: Annual inflation ended 2025 above the 2% target. If rates are cut now, the cost of rent and groceries could spike again just as we were starting to breathe easier.
- The “Soft Landing” Isn’t Over: The economy continues to grow at a steady pace. The Fed fears that if rates are cut prematurely, the economy could overheat.
- Investigations and Tensions: We can’t ignore that Powell is under investigation for the renovation costs of the Fed’s headquarters. To many, this is a pressure tactic from the White House to force his exit or submission.
What This Means for Latino Families in the U.S.
Let’s get to the point. If you’re thinking about buying a home in Florida, Texas, or California, this pause is a message to “wait a little longer.”
- For business owners: Credit won’t get cheaper anytime soon. Plan your inventory assuming capital will remain expensive until at least summer 2026.
- For those sending remittances: A strong dollar (supported by high rates) benefits money transfers to Latin America, as it goes further in pesos or quetzales. But be careful: if the U.S. economy slows due to high rates, jobs in construction and services—key sectors for our community—could take a hit.
“The Fed’s independence isn’t a technical luxury; it’s the shield that prevents your savings from losing value due to electoral whims.” — Hispano Nexus Editorial Analysis.
Image: ElHispanoParaTodos/PRESS